
Market and PAT

The corporate restaurant market in numbers
MEALS
in millions/day
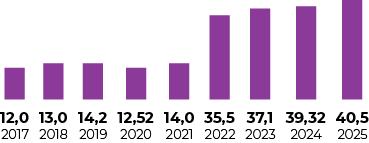
EMPLOYEES
REVENUE
in billions of reais
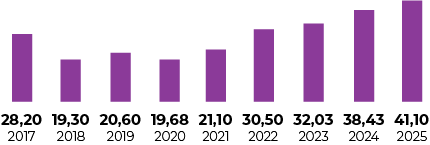
PAT – Worker Meal Program
Exal is based on the Worker Meal Program.
The so-called PAT was established by Law No. 6,321, of April 14, 1976, and is currently regulated by Decree No. 10,854, of November 10, 2021, with complementary instructions established by Ordinance MTP/GM No. 672, of November 8, 2021. The purpose of the Law was to benefit workers with access to food during working hours — from a development and greater business-security perspective, rather than one of an exclusively social nature.
All companies, regardless of the number of employees they have, can and should enroll in PAT, at any time of the year.
Employers wishing to join the Program must complete their enrollment/registration by filling out the enrollment form via the Internet, at the page http://www.trabalho.gov.br/sistemas/patnet/.

Benefits of Participating in PAT
By enrolling your company in PAT, you can benefit from an exemption from payroll charges (INSS, FGTS, among others) on the value of the benefit. In addition, companies that file income tax under the actual profit method can benefit from a tax incentive deduction per meal provided, limited as set forth in the specific Law (Law 9,532/97).
| BENEFITS FOR THE COMPANY | BENEFITS FOR EMPLOYEES |
|---|---|
|
|
The Income Tax Incentive
Subject to the regulatory criteria, a legal entity may deduct from the Income Tax owed, based on actual profit, the amount equivalent to applying the applicable Income Tax rate to the sum of expenses incurred in the execution of PAT, less the employees’ contribution to the cost of meals.
Therefore, the deduction applies “twice”:
- Once, through accounting, on the net amount of expenses incurred as PAT expense, noting that this deduction has no limits;
- The second time, through a direct deduction from the tax owed, subject to the regulatory limits
Deduction Limit
Since 01.01.1998, the direct deduction from the tax, relating to the PAT incentive, is limited to 4% (FOUR PERCENT) of the Income Tax (excluding the surtax). (Law 9,532/97 – Art. 5).
Calculation of the Incentive
The PAT incentive to be deducted directly from Corporate Income Tax (IRPJ) will correspond to the lesser of the following amounts:
- Application of the 15% rate to the sum of the operating expenses incurred with PAT;
- Application of the 4% rate to the amount assessed and owed by the company as IRPJ.
Source: ABERC – Brazilian Association of Group Catering Companies